Blog
How can wearable data improve insurance underwriting?
How wearable data on activity, sleep and heart rate variability can add a current view of risk to insurance underwriting, and what still stands in the way.
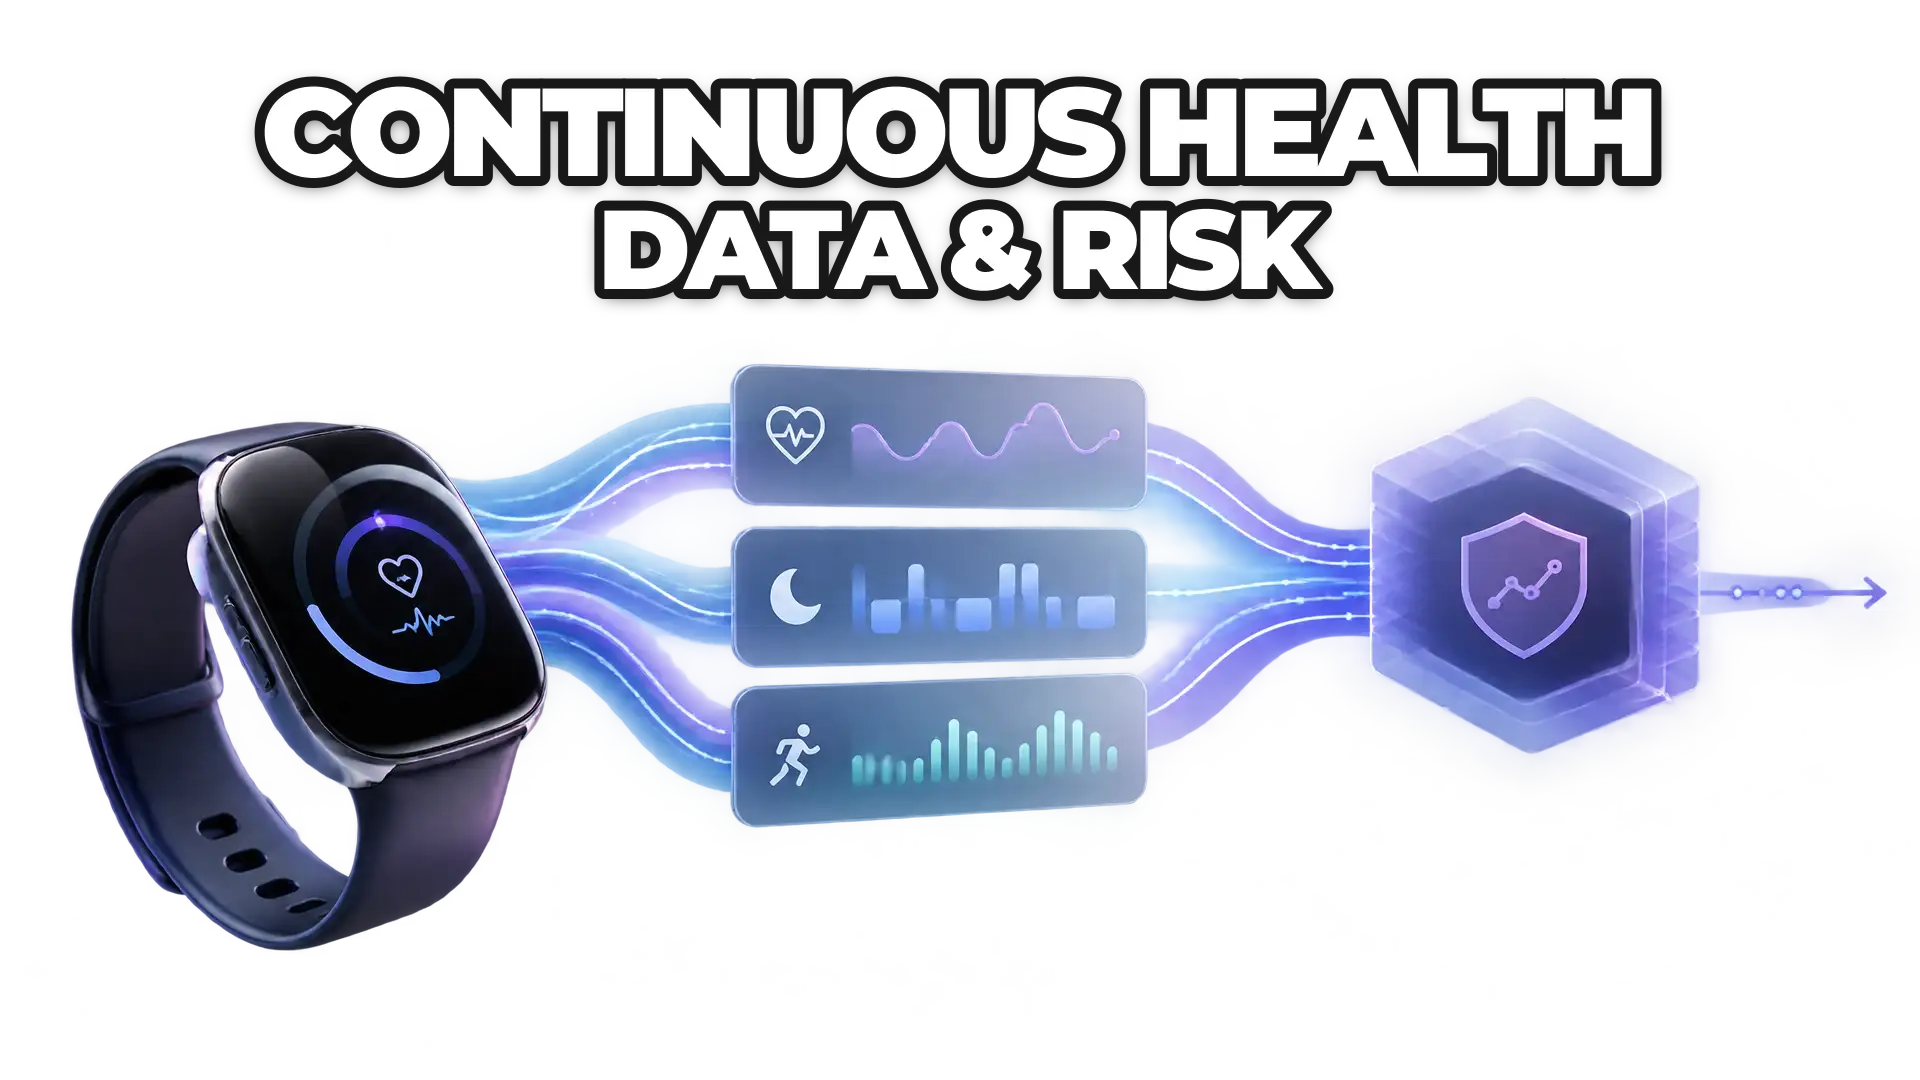
Wearable data can improve insurance underwriting by adding a continuous, current view of a policyholder’s activity, sleep, heart rate variability and recovery to traditional sources such as medical records and family history. That data can inform assessments of mortality and morbidity risk. Four hurdles still limit adoption: inconsistent data formats across devices, privacy and consent rules, consumer trust, and regulatory frameworks that are still developing.
How are wearables used in health tracking today?
Wearables such as Fitbit, Apple Watch, Garmin, Oura, and WHOOP track heart rate, sleep patterns, activity levels, stress, and recovery. This data is used for everything from fitness goals to chronic disease management, but its use in insurance underwriting is still relatively limited.
Wearable data can give insurers a more holistic and dynamic view of a policyholder’s health and habits than traditional methods alone.
What are mortality and morbidity risk?
Mortality risk is the likelihood that a person will die within a certain period. Morbidity risk is the probability that a policyholder develops health conditions that affect quality of life, often leading to long-term medical care, lost income, or disability.
Traditionally, mortality and morbidity risk are calculated from historical data such as medical records, lifestyle factors (smoking, alcohol use), and family history. This data can be incomplete or outdated.
Wearables provide ongoing data that reflects a person’s current lifestyle and habits. By looking at metrics like sleep quality, physical activity levels, and heart rate variability, insurers could see a policyholder’s risk factors more clearly.
How can wearable data improve risk assessment?
Wearable data can improve risk assessment by providing an individualized view of risk that point-in-time underwriting cannot capture:
- Health signals: wearables record signals such as irregular heart rhythm notifications, sleep patterns, or low physical activity, which insurers may weigh as morbidity risk factors.
- Activity tracking: activity levels, calories burned, and exercise frequency give a continuous snapshot of lifestyle choices, which are key factors in mortality and morbidity models.
- Stress and recovery: stress and recovery metrics add a view of wellbeing, which is an increasingly important component of risk models.
- Trends over time: unlike static assessments, wearables offer continuous data that insurers could use to evaluate risk patterns over months or years.
ROOK moves and standardizes the data; it does not diagnose or replace clinical judgment, and underwriting decisions remain the insurer’s.
What are the challenges of using wearable data in underwriting?
Four challenges limit the use of wearable data in underwriting:
- Data privacy and security: insurers must set policies on data ownership, informed consent, and data sharing that comply with regulations like HIPAA in the U.S. or the GDPR (Regulation (EU) 2016/679) in Europe.
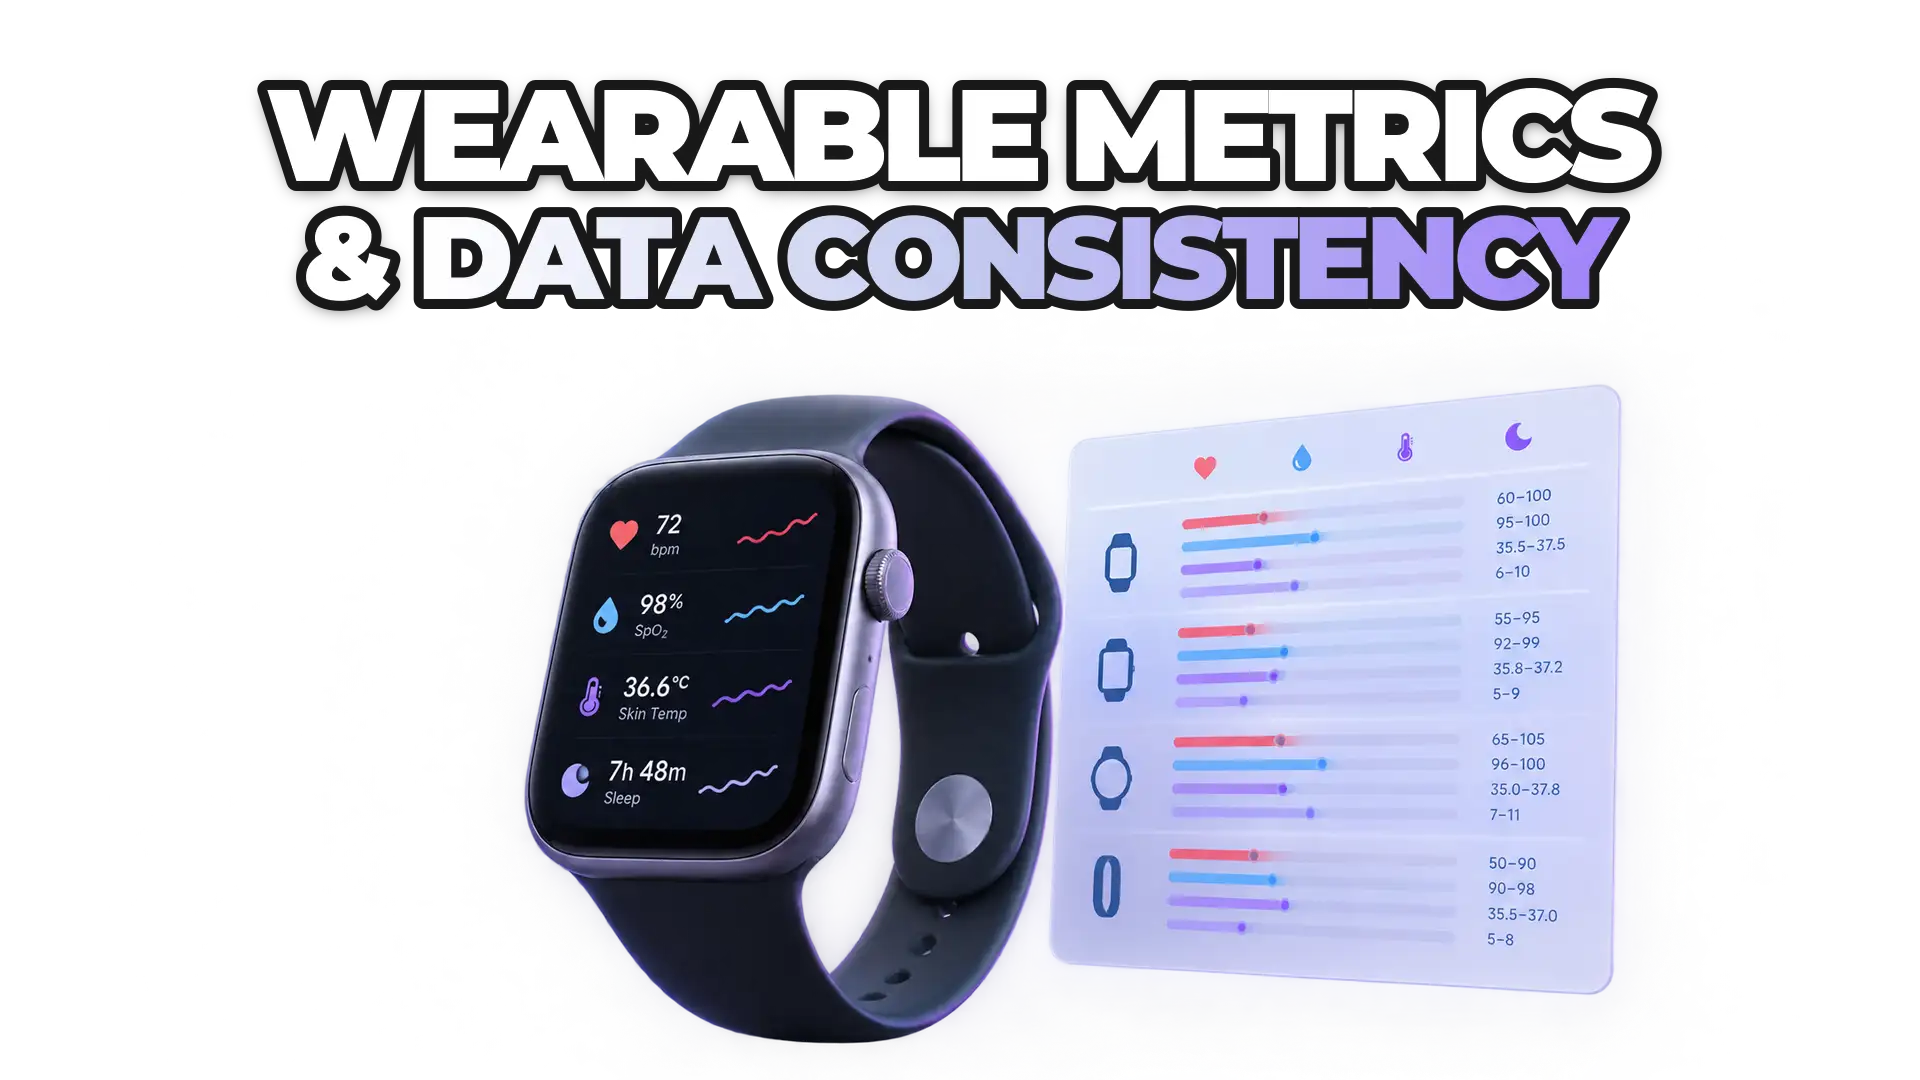
- Standardization of data: different devices and apps use different data formats, which makes data hard to compare. ROOK Connect normalizes data from 72 data sources and more than 500 devices into one format, but broad industry adoption of standardized data is still key.
- Consumer adoption and trust: many consumers are hesitant to share personal health data with insurers, so clear communication on how data is used, stored, and protected is essential.
- Regulatory hurdles: insurance regulators still need clear guidelines on how wearable data can be used in underwriting decisions, ensuring fairness and transparency for consumers.
For how ROOK handles health data, ROOK operates under a HIPAA-aligned security program, signs BAAs with covered entities, and processes EU personal data under GDPR as a data processor.
What is the future of wearables in insurance underwriting?
Wearable data could make underwriting more dynamic and individualized, supporting better pricing, fewer claims, and more tailored policies for consumers. If the industry can tackle data privacy, standardization, and consumer adoption, wearable data could become a key tool in building more accurate and personalized insurance models.
As wearables improve and become more common, insurers that adopt this data early may gain an advantage, but only if the industry addresses data standardization, privacy, consumer trust, and regulation. For a deeper look, see wearable data in insurance underwriting, or start with the ROOK developer documentation.
 Written byDaniel MasDigital Marketing Lead