Blog
How are AI and wearable data changing insurance underwriting?
Wearable data gives insurers continuous activity, sleep, and heart rate signals, and AI turns them into indicators for risk assessment and wellness programs.
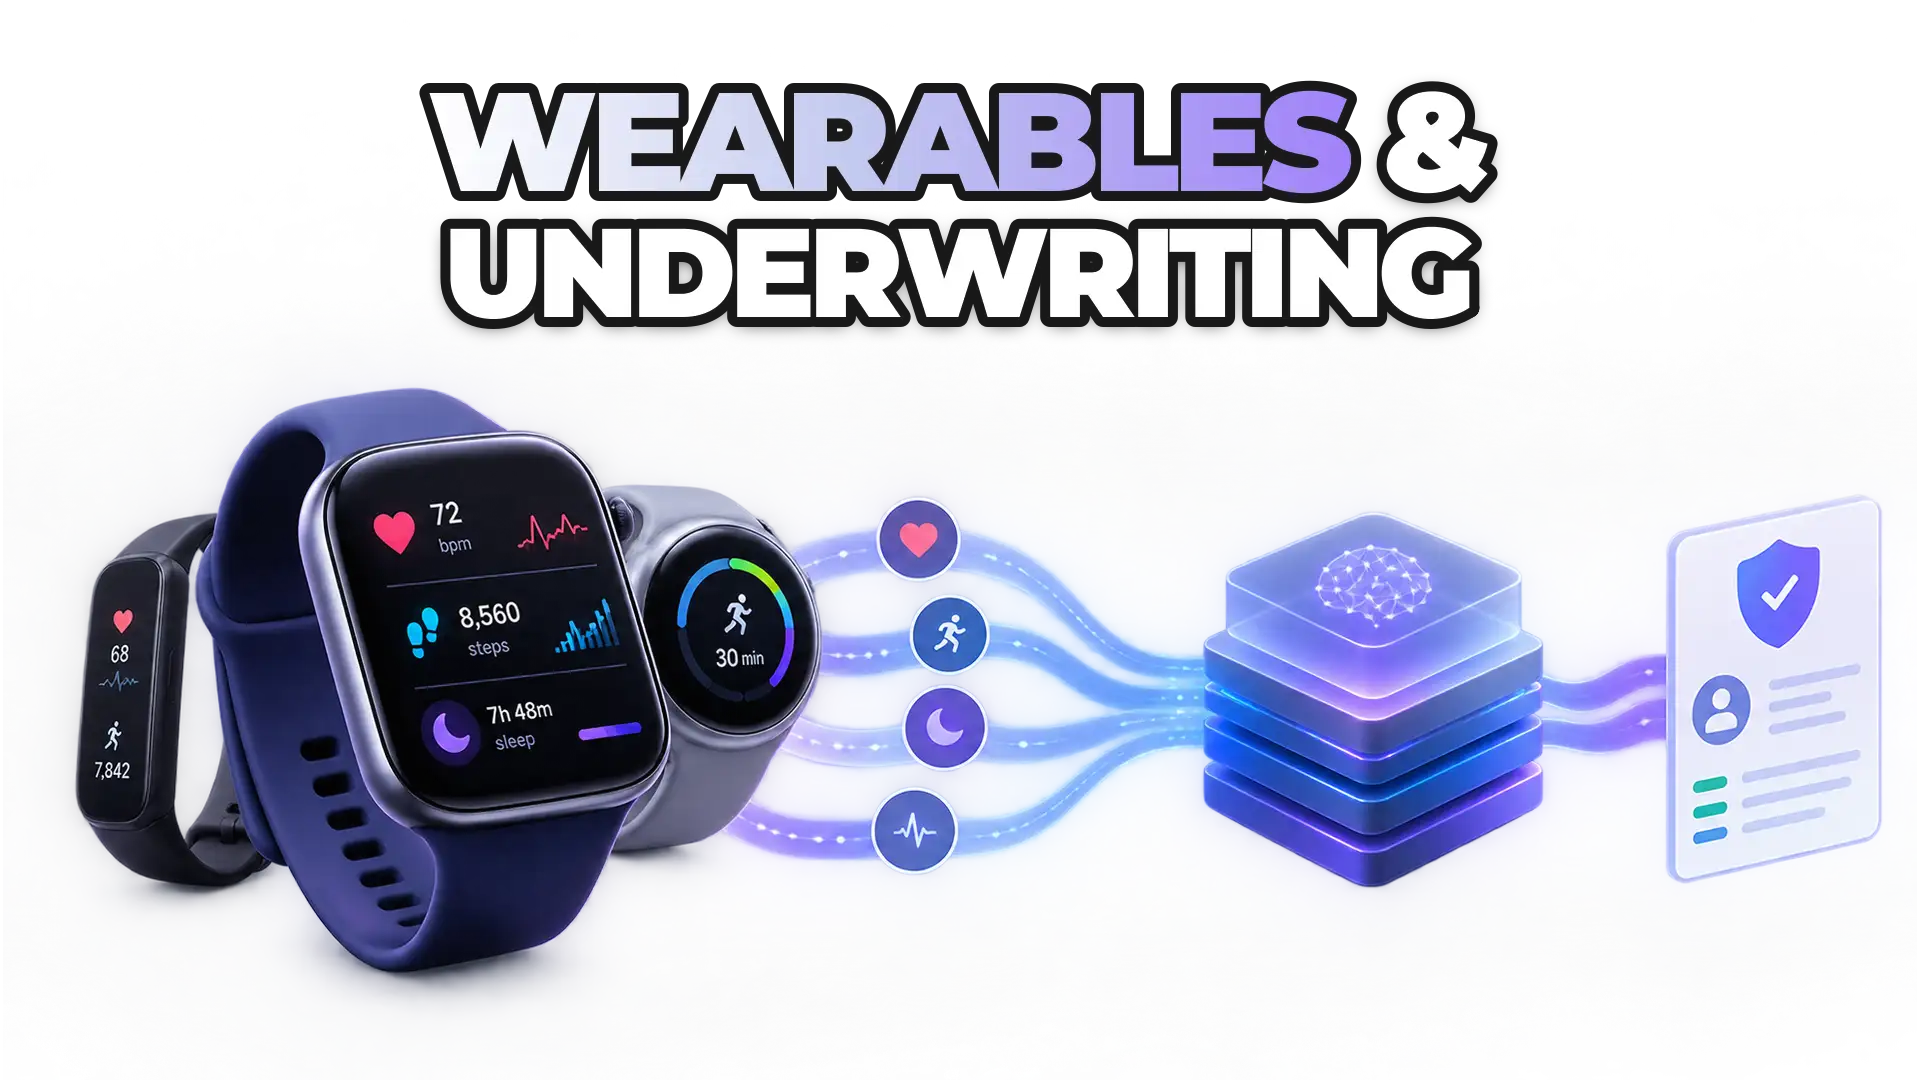
AI and wearable data are moving insurance underwriting from static questionnaires and one-time medical exams toward continuous, real-world signals. Wearables capture activity, heart rate, HRV, sleep, and stress over time. AI models standardize those signals across devices and turn them into indicators insurers can use for risk assessment, pricing, wellness programs, and claims review. Raw device data alone is not enough.
How does wearable data change traditional underwriting?
Wearable data replaces snapshots with continuous signals. Traditional underwriting relies on a medical exam, a survey, or a historical record, which quickly become outdated and often miss daily behavior.
Wearables provide continuous, real-world signals, including:
- Activity levels and movement patterns
- Resting and active heart rate
- HRV (heart rate variability)
- Sleep regularity and sleep quality
- Stress patterns
- Glucose levels (for supported sensors)
- Body temperature and recovery signals
Combined with AI, these metrics give insurers a more current and dynamic view of risk. For the business case, see wearable data in insurance underwriting.
How does AI turn raw wearable data into health indicators?
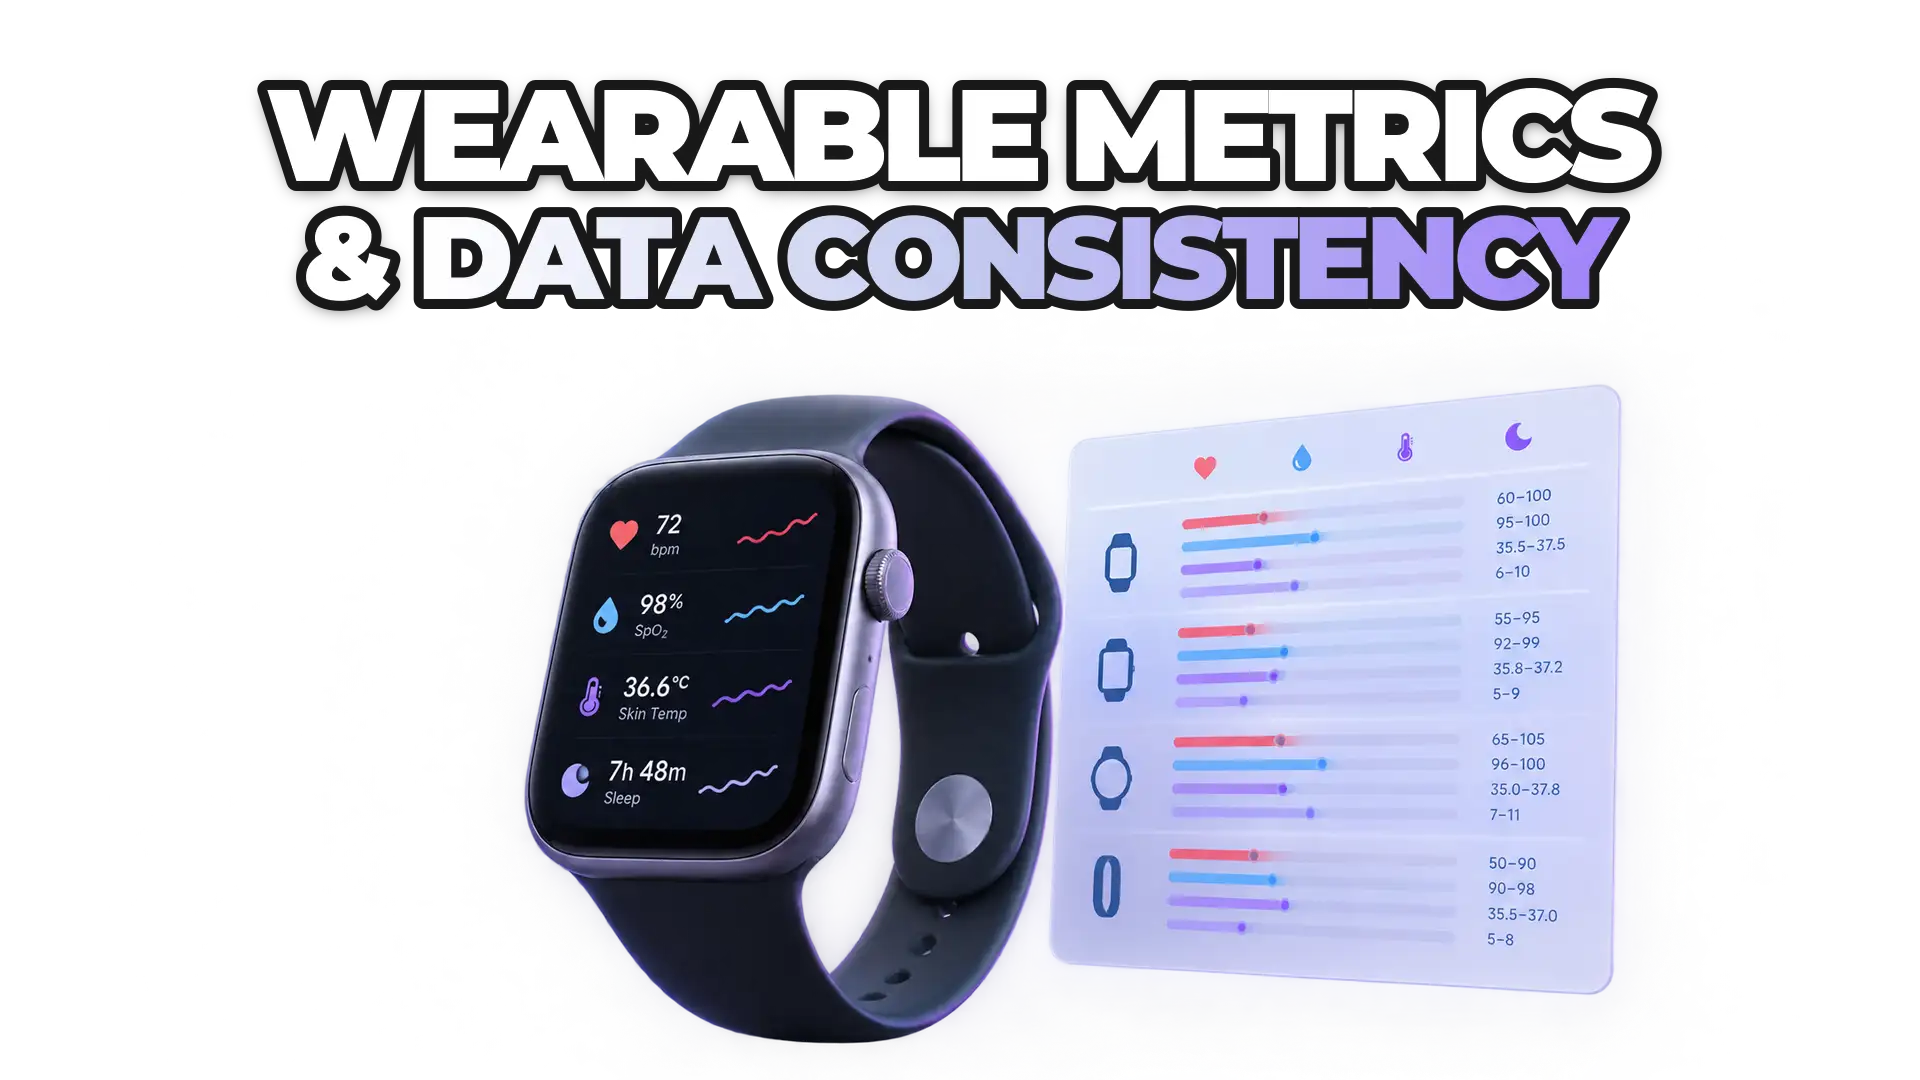
AI turns wearable data into usable indicators by standardizing it, because each device brand uses different sensors, algorithms, and measurement methods.
AI models address this by:
- Normalizing and standardizing metrics across device types
- Filtering noise and correcting inaccuracies
- Identifying behavioral patterns associated with long-term health
- Estimating risk from historical and recent signals
Insurers can then base decisions on validated health indicators, not just raw metrics.
What can AI models find in wearable data for underwriting?
Insurers' AI models can look for wearable patterns associated with long-term health factors, such as:
- Cardiovascular risk factors
- Metabolic health trends
- Stress response and resilience
- Sleep patterns
- Lifestyle-related risk factors
These insights can help insurers classify risk more precisely and design pricing that reflects real behavior. Wearable signals are not diagnoses; the risk model and its conclusions belong to the insurer. ROOK moves and standardizes the data; it does not diagnose or replace clinical judgment.
How does wearable data support engagement and wellness programs?
Wearable data lets insurers build preventive, member-centric programs, not just better risk assessment.
Insurers can use AI to deliver:
- Personalized wellness recommendations
- Incentive-based behavior programs
- Frequent feedback loops
- Alerts the insurer defines on member signals
Well-designed programs can increase member engagement. Learn more about quantifying wellbeing in insurance with wearable data.
Can wearable data help reduce fraud and improve claims accuracy?
AI-enhanced wearable data gives insurers new ways to:
- Spot inconsistencies between reported and observed behavior
- Support claims review with physiological data
- Identify irregular patterns
- Improve transparency in wellness-based reward systems
These capabilities can support more accurate assessments and trust between insurers and members.
Can wearable data make underwriting more inclusive?
Wearable data can widen access because traditional underwriting often excludes people who lack historical medical records, or who had past conditions but have since adopted healthier habits.
AI-powered wearable data allows for:
- More inclusive insurance options
- Dynamic pricing based on current behaviors
- Coverage opportunities for underserved populations
By considering current health signals alongside medical history, insurers can expand access while managing risk.
What does this mean for the future of underwriting?
Wearables and AI are turning underwriting from a static process into a continuous assessment of real-world signals. Insurers that adopt the shift can work toward:
- More precise risk evaluation
- Smarter pricing models
- Stronger customer engagement
- Lower operational costs
As wearable adoption grows, standardized health data will become a foundational input for modern insurance. To see how ROOK Connect delivers normalized wearable data to insurers, start with the ROOK developer documentation.
 Written byDaniel MasDigital Marketing Lead