Blog
Can Wearable Data Improve Insurance Risk Models?
RGA's UK Biobank analysis links walking pace and step counts to mortality risk. Here is what that means for insurers using wearable data.
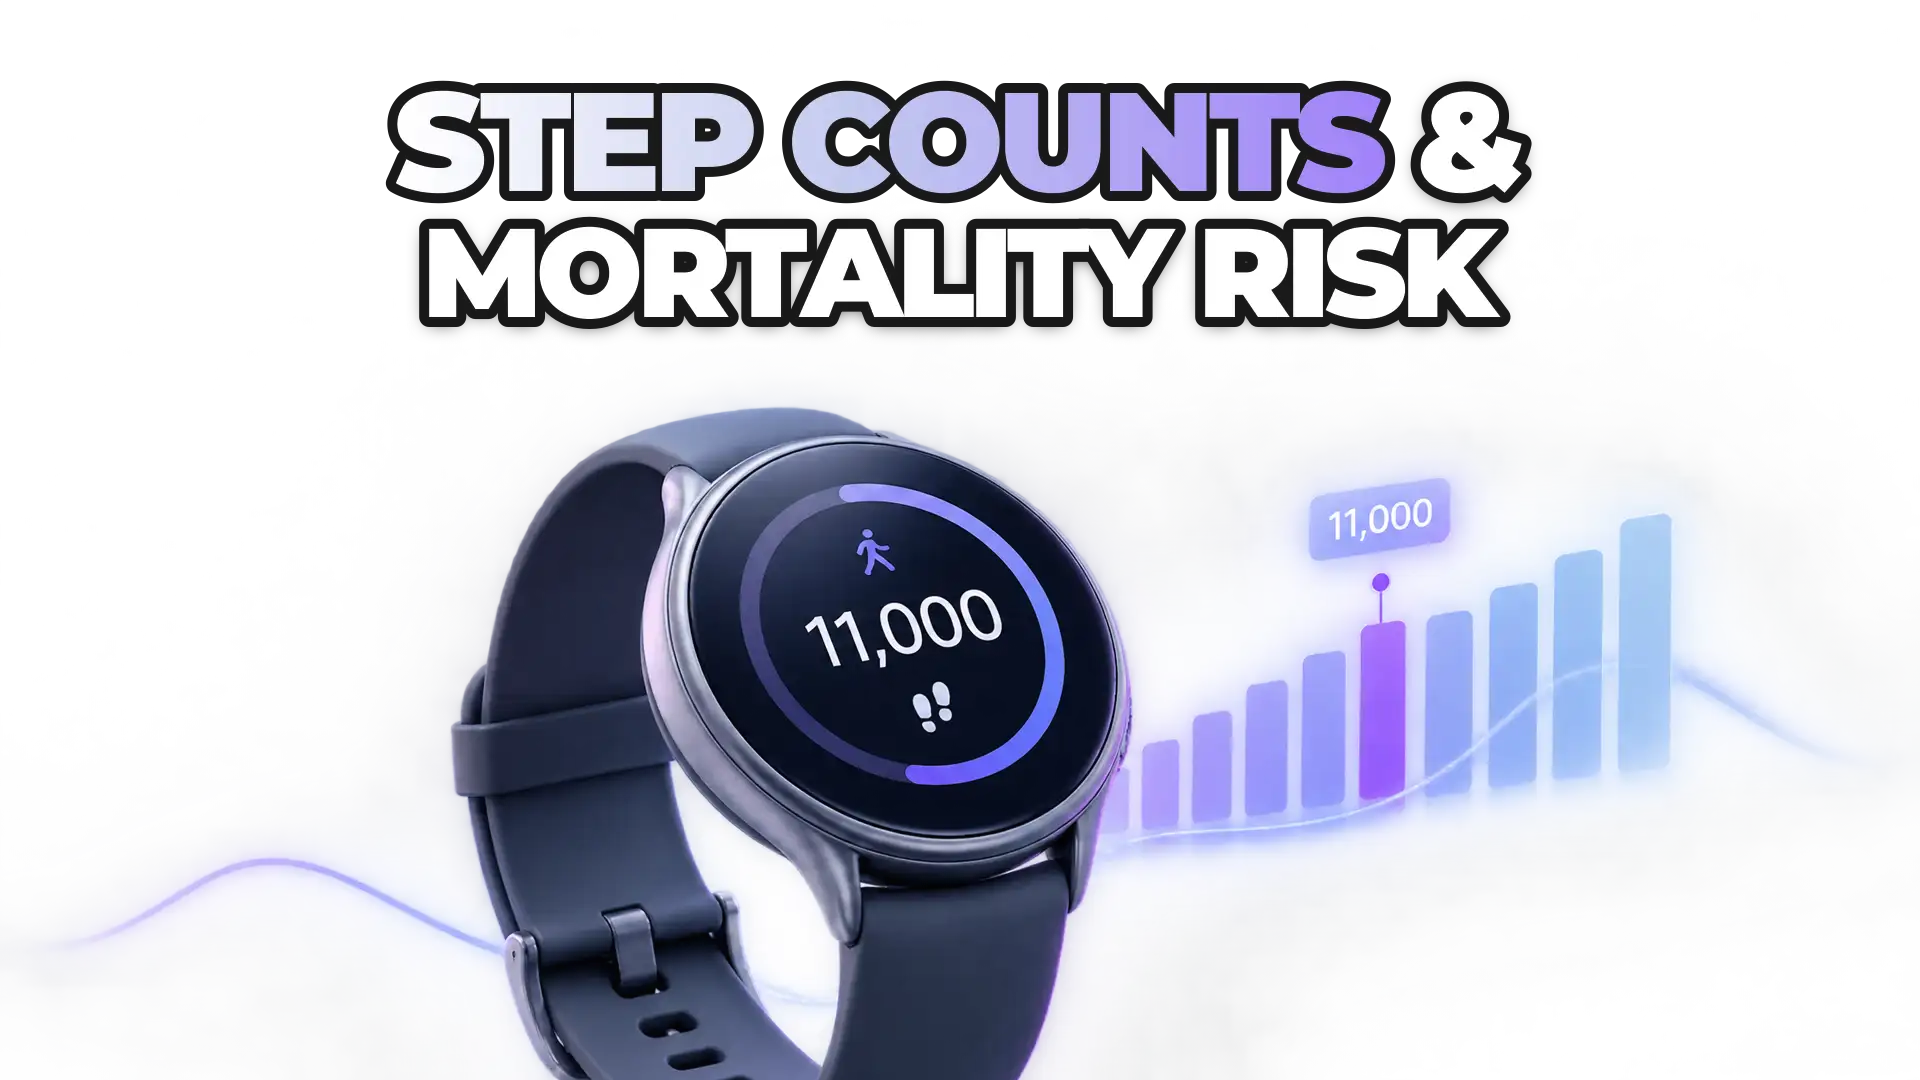
An RGA-sponsored analysis of the UK Biobank study, with the University of Leicester, found that lifestyle data can add to traditional risk factors in insurance risk models. Participants with a brisk walking pace had up to 50% lower mortality risk than slow walkers, and those averaging about 11,000 steps a day had lower mortality risk than those averaging 5,000. BMI remained a strong predictor.
The insurance industry has long relied on traditional risk factors such as body mass index (BMI), blood pressure, and cholesterol to estimate health outcomes. These metrics are well established in the general population, but insurers have often struggled to quantify their impact in insured lives. The RGA analysis of UK Biobank data incorporates both traditional and non-traditional health indicators into risk models.
How do traditional and non-traditional risk factors compare?
RGA's study confirms that BMI continues to be a strong predictor of mortality risk, with a U-shaped relationship: very low and very high BMI values were associated with nearly three times the mortality risk of mid-range values.
The RGA study also highlights non-traditional risk factors:
- Self-reported walking pace: individuals who reported a brisk walking pace had up to a 50% lower risk of mortality than those with a slow pace.
- Wearable-measured step counts: participants averaging around 11,000 steps per day had lower mortality risk than those averaging 5,000 steps.
According to RGA, lifestyle behaviors captured through simple metrics like walking pace and step counts can add predictive value alongside traditional biomarkers such as blood pressure and cholesterol.
What does the RGA study mean for insurers?
For insurers, wearable-derived metrics could change how underwriting and wellness programs work. According to RGA's analysis:
- Non-traditional data improves the ability to segment risk.
- Health and activity data can engage policyholders directly and encourage healthier behaviors.
- The UK Biobank is representative of insured populations, which makes the findings relevant for underwriting models.
By combining traditional and new forms of health data, insurers can move from static risk assessment toward continuous data. For more on this use case, see wearable data in insurance underwriting.
How does ROOK help insurers use wearable data?
ROOK connects insurers to standardized data from 72 data sources and more than 500 devices through one API, turning raw activity and biometric signals into consistent documents. This allows companies to:
- Bring step counts, sleep, and biometrics into their models in one format.
- Deliver personalized wellness programs based on real-world behaviors.
- Reduce the operational complexity of managing multiple integrations.
ROOK moves and standardizes the data; it does not diagnose or replace clinical judgment. Risk models and underwriting decisions remain the insurer's own.
Why combine traditional and lifestyle data for risk assessment?
RGA's UK Biobank study indicates that combining traditional metrics like BMI with lifestyle data such as walking pace and step counts gives a more complete view of health and longevity. For insurers, that can strengthen underwriting and position them as partners in policyholders' health.
ROOK's role is to make the data behind these models accessible and consistent. To see the data structure, start with the ROOK developer documentation.
References/Source:
RGA: Quantifying Wellbeing in Insurance – What are the keys to a longer life?
 Written byDaniel MasDigital Marketing Lead