Blog
How Is Predictive Analytics Changing the Insurance Industry?
How predictive analytics and digital-first strategies change insurance risk assessment, premium pricing, sales, underwriting, and claims processing.
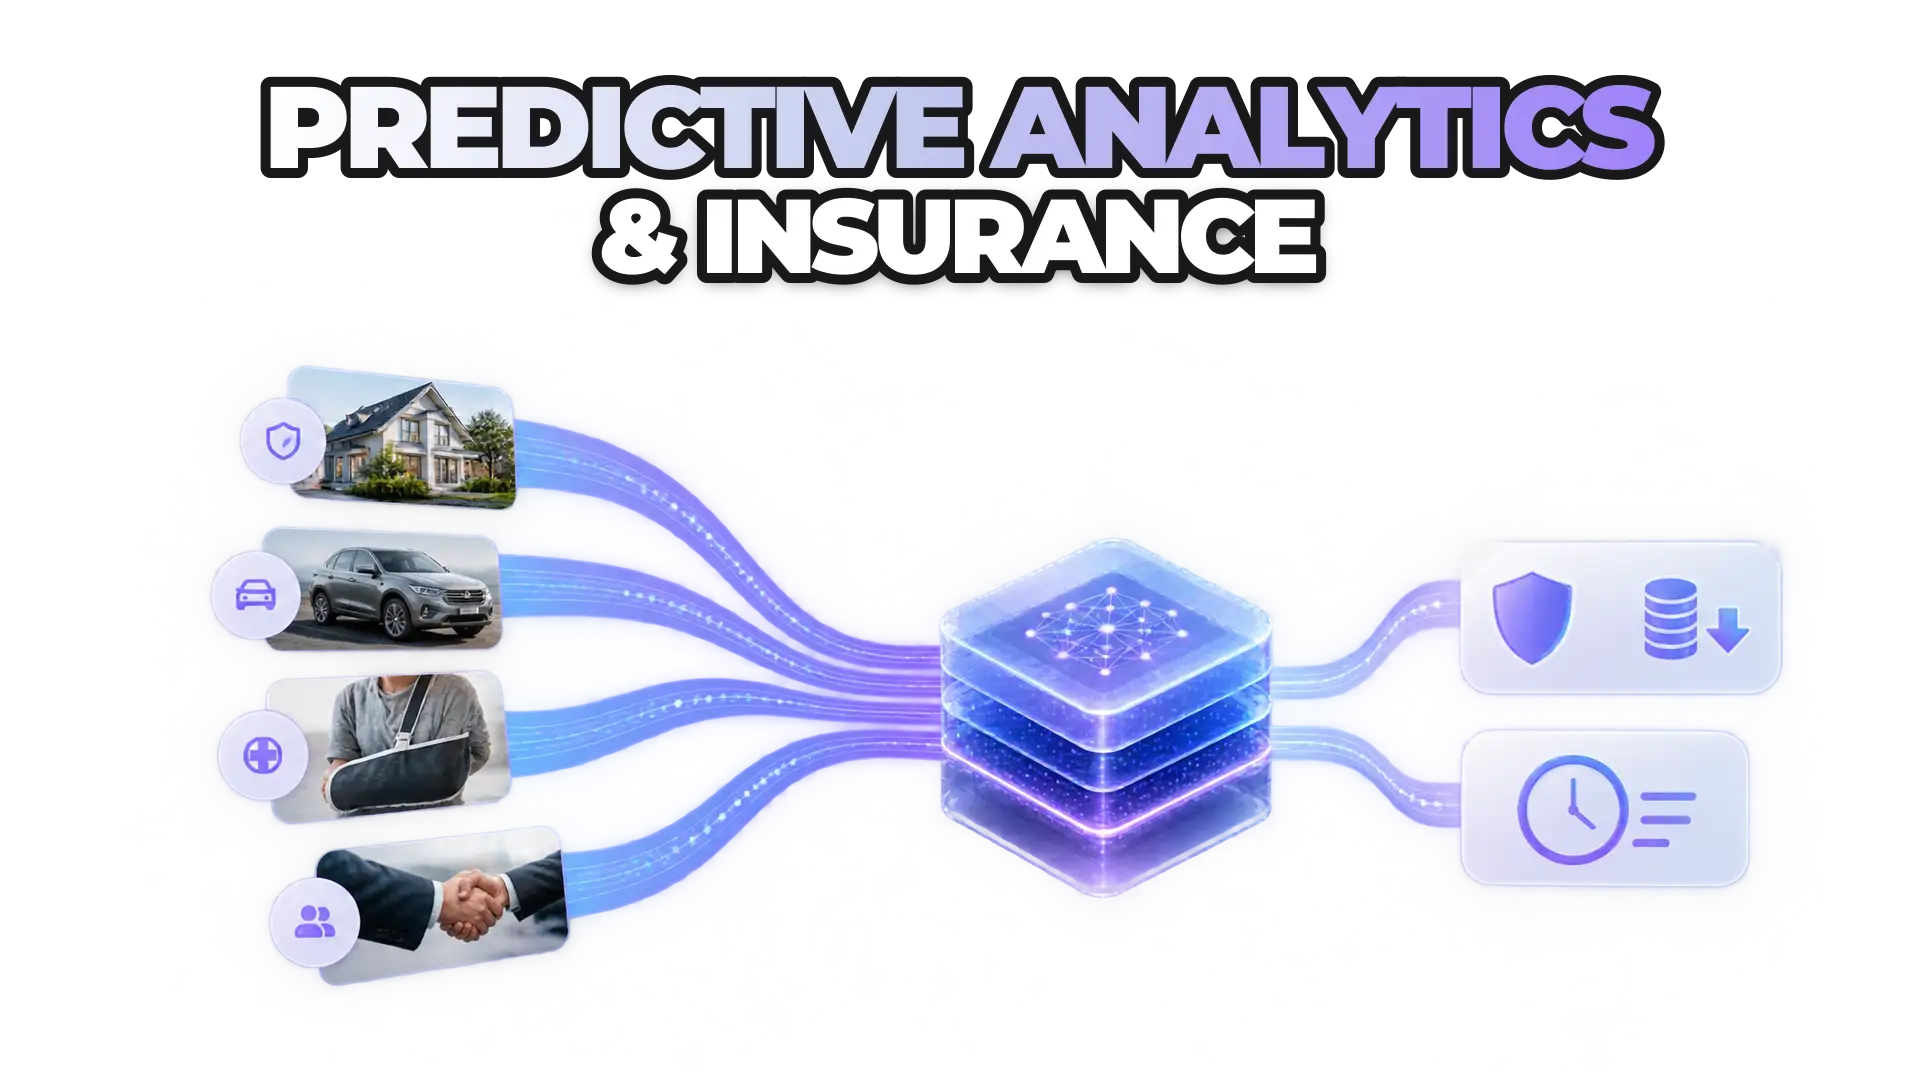
Predictive analytics and digital-first strategies help insurers in four areas. In risk assessment, more precise risk calculations produce premiums that reflect true risk and attract a broader customer base. In sales, AI-driven insights personalize digital interactions for younger consumers. In underwriting, predictive models identify and mitigate risks more accurately and at lower cost. In claims, faster data access and analytics shorten processing times and enable personalized resolutions.
This is the second post in ROOK's series on wearable data in insurance. The first post covers how wearable technology and health data are changing insurance.
How does predictive analytics improve insurance risk assessment?
Predictive analytics improves insurance risk assessment by enabling more precise risk calculations and informed decision-making, which helps insurance companies whose outdated risk assessment models make competitive rates hard to set.
Refining risk calculations: Predictive analytics provide clearer insights into potential risks. For example, Guardian Group’s collaboration with Sutherland was estimated by Sutherland to reduce manual efforts by 25% and claims-related processing time by 20%.
Accurately priced premiums: With better risk assessments, insurers can offer premiums that accurately reflect true risk, resulting in competitive rates that attract more customers.
Attracting a broader customer base: Accurate pricing appeals to a wider audience, enabling insurers to lead the market with fair and transparent policies.
How do digital-first sales help insurers reach younger customers?
Digital-first sales interactions, supported by AI-driven insights, help insurers engage younger, tech-savvy consumers, whom sales models without digital-first support struggle to reach.
Enhancing digital sales interactions: AI provides insights and personalized recommendations that make digital sales channels more effective.
Meeting consumer demands: Younger consumers expect digital-first experiences. Insurers use technologies like telematics in auto insurance to encourage safer driving behaviors and meet these expectations.
How does predictive analytics change insurance underwriting?
Predictive analytics makes underwriting more accurate and efficient than traditional underwriting processes, which are slow, costly, and unable to adapt to new data sources.
Accurate risk assessments: Predictive models help insurers identify and mitigate risks more effectively, for example by giving feedback on risky driving maneuvers.
Cost savings: Streamlining underwriting processes through predictive analytics saves resources and reduces costs.
Efficiency: Companies adopting predictive underwriting models report significant cost reductions and operational improvements.
How do analytics speed up insurance claims resolution?
Data access and analytics speed up claims resolution by replacing manual claims processes, which often lead to delays and generic resolutions that frustrate customers.
Faster claims processing: Faster access to claims data reduces delays, leading to quicker claims resolution and more satisfied customers.
Personalized claims resolution: Tailored resolutions show customers they are valued. For example, Sutherland’s analytics solutions achieved 100% digitization of forms, significantly reducing processing times.
Customer satisfaction: Faster and more efficient claims processes translate to positive customer experiences and loyalty.
Why does adopting AI and wearable health data matter for insurers?
The slow pace of technological integration is a critical challenge for the insurance industry, and adopting technologies such as AI-driven claims processing and wearable health data can redefine success.
Informed decisions: Timely data helps insurance companies make accurate, data-driven decisions. ROOK moves and standardizes wearable data; it does not make underwriting, pricing, or health decisions, which remain with the insurer.
Improved efficiency: Integrated technologies streamline operations, reduce costs, and improve customer satisfaction.
Staying relevant: Keeping pace with technological change keeps insurers competitive in a dynamic market.
What results have companies seen from predictive analytics and digital tools?
Sutherland estimated that Guardian Group would reduce manual efforts by 25% and claims processing time by 20%. Similarly, Light-it used ROOK’s API to create Vitality, a HealthTech app that integrates data from multiple medical devices, without significant technical investment. For more on that collaboration, see how Light-it and ROOK partner on healthcare innovation.
The next post in this series covers the top challenges of integrating wearable data in insurance and strategies to address them. To try wearable data integration yourself, open a ROOK sandbox account in the ROOK Portal.
 Written byJonas DückerCMO | COO